
Timothy A. Hoyle, Chief Investment Officer
thoyle@haverfordquality.com
Finding Ballast for Choppy Markets
Markets navigated a difficult week as oil prices surged alongside 10-year Treasury yields. Unfortunately, the view ahead also looks far from smooth sailing. We believe investors should brace for continued near-term volatility as markets confront a number of headwinds, both new and ongoing.
Two lingering concerns remain at the forefront. First is rising yields. The 10-year Treasury is yielding near 5%, and sticky core inflation and rising energy prices prompted a September rate hike. Since history suggests that rate hikes are rarely, if ever, "one and done," Fed uncertainty is likely to keep markets on edge as investors grapple with higher rates across the yield curve.
The second is rising oil prices as escalating Middle East tensions and the Russia-Ukraine war continue to disrupt supply. In addition to paying more at the pump, consumers are feeling the knock-on effects of record-high diesel prices on shipping, agriculture, and other industries. Higher energy prices and pass-through inflation effects make the Fed's job more difficult.
As if those were not enough, new sources of turbulence have emerged. The fractious U.S. midterm election cycle is likely to exacerbate domestic tensions and market angst over the ensuing weeks. In an even stranger plot twist, former champions of AI, from technology executives to politicians, have suddenly turned against frontier models, warning of dire risks and doomsday scenarios while calling for industry guardrails and increased regulations. Some Chinese policymakers are also sounding alarms, even as they chastise U.S. negativity while aiming to push ahead in the AI race. Rising backlash against data centers has also emerged, unifying communities and local politicians in opposition. Anti-AI rhetoric is likely to remain a recurring theme in candidates' campaign platforms this election.
Cynics view the sudden anti-AI groundswell as either an industry tactic to suppress competition and craft regulation in its favor, or as a political ploy to drive voter turnout. Whether these issues fade after the November elections remains to be seen. Until then, hyperscalers may be subject to increased scrutiny, and data center development could slow, although we do not believe materially so. Longer term, these trends ultimately may improve return on investment (ROI) by encouraging a more discriminating, methodical AI build out and replacing the manic, winner-take-all spending spree that has been driving up prices. However, while technology is typically a volatile sector, we expect even greater volatility in technology stock prices through the fourth quarter.
In contrast, quarter-to-date returns for higher-quality and dividend-paying stocks generally have been steady. These stocks may offer potential ballast against tech sector gyrations, helping to dampen portfolio volatility. And if the AI trade falters, these stocks could be an important source of downside protection.
Semiconductor Stocks versus Dividend-Paying Stocks
July 1, 2026 – September 15, 2026
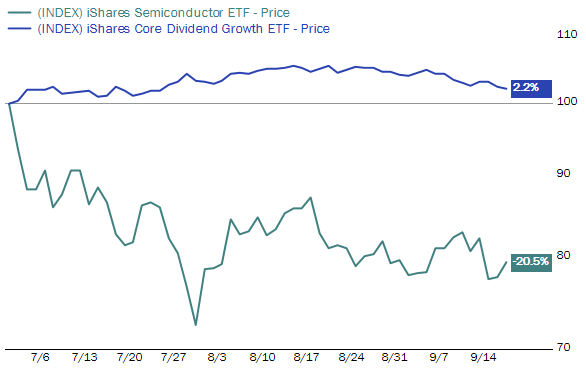
Weekly Market Commentary_Semiconductors vs Quality Dividends Chart
Sources: FactSet; Haverford Trust
While the Fed and U.S. midterm elections may drive stock prices in the near term, we continue to believe that AI will be the theme that matters most over the medium to longer term. Tremendous demand for computing power remains as AI-enabled tools permeate our business and personal lives.
Media Inquiries
Veronica McKee, CMP
Direct Phone: 610.995.8758
Email: vmckee@haverfordquality.com
Katie Karsh
Direct Phone: 610.755.8682
Email: katie@gobraithwaite.com
Disclosure
These comments are provided as a general market overview and should not be relied upon as a forecast, research or investment advice, and is not a recommendation, offer, or solicitation to buy or sell any securities or to adopt any investment strategy. Opinions expressed are as of the date noted and may change at any time. The information and opinions are derived from proprietary and non-proprietary sources deemed by Haverford to be reliable, but are not necessarily all-inclusive and are not guaranteed as to accuracy. Index returns are presented for informational purposes only. Indices are unmanaged, do not incur fees or expenses, and cannot be invested in directly.
Investments in Securities are Not FDIC Insured · Not Bank Guaranteed · May Lose Value
Related News & Insights
The hype in Artificial Intelligence (AI), what many say, is a modern-day gold rush, is amassing trillions of dollars of investment. A recent UN Trade and Development (UNCTAD) report projects the global AI market will grow from $189 billion in 2023 to $4.8 trillion by 2033; massive gains and insatiable demand is being seen in all corners of the industry.
John F. Thomas, CFA Vice President, Fixed Income Portfolio Manager jthomas@haverfordquality.com Hut, Hut, Hike? [...]
While New Year’s resolutions are likely long forgotten, it is never too late to [...]
