
Timothy A. Hoyle, Chief Investment Officer
thoyle@haverfordquality.com
Rotation Replaces Risk-Off in October
AI is currently at the epicenter of every newsworthy item from equities to elections. It is even dominating fixed income markets as hyperscalers, citing an overarching concern of falling short on compute, race to issue debt to finance data center buildouts. This dominance has resulted in an extremely narrow equity market driven by a handful of mega-cap tech names, overshadowing nearly everything else. Such a narrow market environment creates concern that corrections in these mega-cap tech stocks will drag down the broader market. However, October proved different.
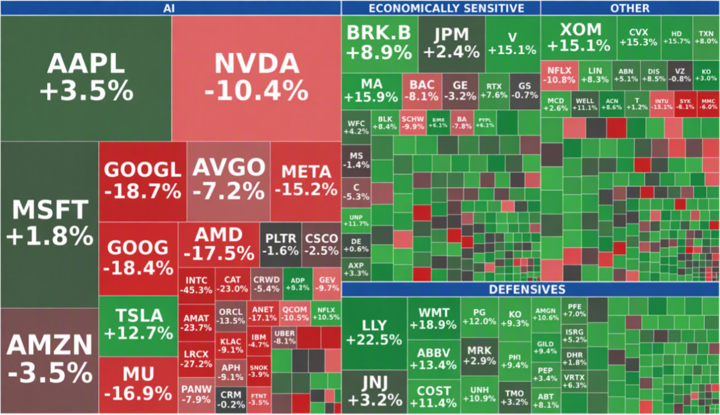
October saw several steep corrections in the AI complex, contributing to a -5.3% decline in the Nasdaq and a -0.9% drop in the S&P 500 for the month. However, these headline returns obscured an important change beneath the surface. Rather than a risk-off month, October revealed a strong and swift rotation into overlooked sectors. Sizable declines in tech companies were offset by broader resilience, evidenced by the equal-weight S&P 500 Index rising nearly 5%, with 9 of 11 sectors in the index advancing. Energy, Consumer Staples, Utilities, and Health Care each advanced roughly 10% or more, offsetting weakness in the AI trade and helping to mitigate overall losses for the index. We view this broadening of market participation as a constructive development, following an extended period in which returns were increasingly concentrated among a relatively small group of technology companies. Although the AI trade weakened, the rest of the market finally began to carry more of the load.
In light of AI's dominance, Haverford has adopted a general way of viewing portfolio exposure and risk by segmenting the market into four groups: AI, Defensives, Economically Sensitive, and Other, which includes the rest of Tech, Energy, and real assets. The AI group of 50 AI-centric companies, representing approximately 50% of the S&P 500, declined close to -8% in October, with only 31% of those companies producing positive returns for the month. Outside this group, however, participation was dramatically stronger. We saw 91% of Defensives, 72% of Economically Sensitive, and 72% of Other stocks advance in October. Rather than a broad risk-off move, October appears to have produced a notable change in market leadership, with capital rotating toward areas that had previously participated less fully in the AI-led advance.
Heatmap of October 2026 S&P 500 Index Returns by Category
As of October 31, 2026
Oct 2026 S&P Heatmap
Sources: FactSet, Haverford. Economically Sensitive includes Industrials and Financials. Defensives include Staples and Health Care. Other includes Energy, Commodities, Real Estate, and non-AI technology.
Investment Implications
The recent pressure on AI-related stocks reflects legitimate questions about the enormous amount of capital required to fund the infrastructure buildout and the potential returns that spending will ultimately generate. Rising debt and equity issuance, along with Anthropic’s anticipated IPO, are also creating greater competition for investor capital.
We believe two things can be true at the same time. The unprecedented pace of AI investment will likely lead to overbuilding and financial stress among some leveraged participants. However, that does not mean the investment itself will prove uneconomic. We continue to believe this capital-spending cycle will create meaningful productivity gains, new revenue opportunities, and ultimately stronger earnings growth across the economy.
We also believe diversification beyond AI may be constructive in two ways. First, supported by strong fundamentals, many quality companies potentially stand to benefit as earnings growth and productivity gains broaden beyond the narrow set of current AI leaders. Second, October stands as an encouraging reminder that the market—and investors—can still do well even during these inevitable periods of retrenchment around AI. October’s strong market rotation helped many diversified equity portfolios deliver positive returns in the face of the broad market’s decline, while providing downside protection against corrections in the AI trade.
Media Inquiries
Veronica McKee, CMP, CMM
Direct Phone: 610.995.8758
Email: vmckee@haverfordquality.com
Katie Karsh
Direct Phone: 610.755.8682
Email: katie@gobraithwaite.com
Disclosure
These comments are provided as a general market overview and should not be relied upon as a forecast, research or investment advice, and is not a recommendation, offer, or solicitation to buy or sell any securities or to adopt any investment strategy. Opinions expressed are as of the date noted and may change at any time. The information and opinions are derived from proprietary and non-proprietary sources deemed by Haverford to be reliable, but are not necessarily all-inclusive and are not guaranteed as to accuracy. Index returns are presented for informational purposes only. Indices are unmanaged, do not incur fees or expenses, and cannot be invested in directly.
Investments in Securities are Not FDIC Insured · Not Bank Guaranteed · May Lose Value
Related News & Insights
AI's dominance has resulted in an extremely narrow equity market driven by a handful of mega-cap tech names, creating concern that corrections in these stocks will drag down the broader market. However, October proved different. Although the AI trade weakened, the rest of the market finally began to carry more of the load.
With just days until the U.S. midterm elections, it is nearly impossible to escape the political news cycle. However, election results historically have had less impact on market performance than political candidates would have one believe.
The U.S. equity bull market just turned four years old. One defining characteristic of this bull market, and of growing concern to many investors, is its lack of breadth. Historically, narrow market leadership has often been viewed as a warning sign, raising concerns that the market’s foundation may be weaker than headline index returns suggest.
