
Maxine Cuffe, Vice President, Director of Global Strategies
mcuffe@haverfordquality.com
Timothy A. Hoyle, Chief Investment Officer
thoyle@haverfordquality.com
Halie O’Shea, Vice President, Director of Research
hoshea@haverfordquality.com
The AI Trade Is Far from Over
Election offers a referendum, not a moratorium, on AI
AI-related stocks have been volatile both before and after the U.S. election. Even before voters went to the polls, investors were questioning the return on investment (ROI) from massive capital spending (capex) and the growing debt obligations tied to data center buildouts. The results of the mid-term elections, a blue tsunami, suggest that voters are concerned about the Iran war, AI buildout, and how both are playing into the ultimate issue of affordability. We expect greater scrutiny and an increased regulatory burden on AI data center spending as state governors look to deliver on election promises.
Much of the AI complex is currently trading in bear market territory, down over 20% from their 52-week highs. Microsoft and Apple remain the exceptions, trading close to all-time highs. The fundamentals, however, tell a different story. Recent earnings reports were strong. And while supply concerns—around chips, components, construction resources, and more—have been cited frequently, not a single major AI company has said one negative word about demand. Increased regulation may emerge, and data center activity may shift toward more accommodative states. However, we expect strong demand for compute to continue as enterprises increasingly recognize the outsized potential for productivity gains and the competitive edge that AI can provide.
Valuations suggest skepticism, not exuberance
Current valuations reveal that the market appears to be giving little credit to the sustainability of AI-related earnings. Looking at some of the top stocks in the S&P 500, Micron is trading at roughly 4 times forward earnings, Broadcom at about 17x, and both Alphabet and Meta are below 20x, as of November 11, 2026. Apple, at around 37x, has been treated as a more defensive holding because of its lower capex spending. This is a markedly different profile from the technology bubble of late 1999, when companies like Cisco sold for well over 100x earnings, and it took about 15 years to work off that valuation.
Select Mega Cap Stocks
As of November 10, 2026
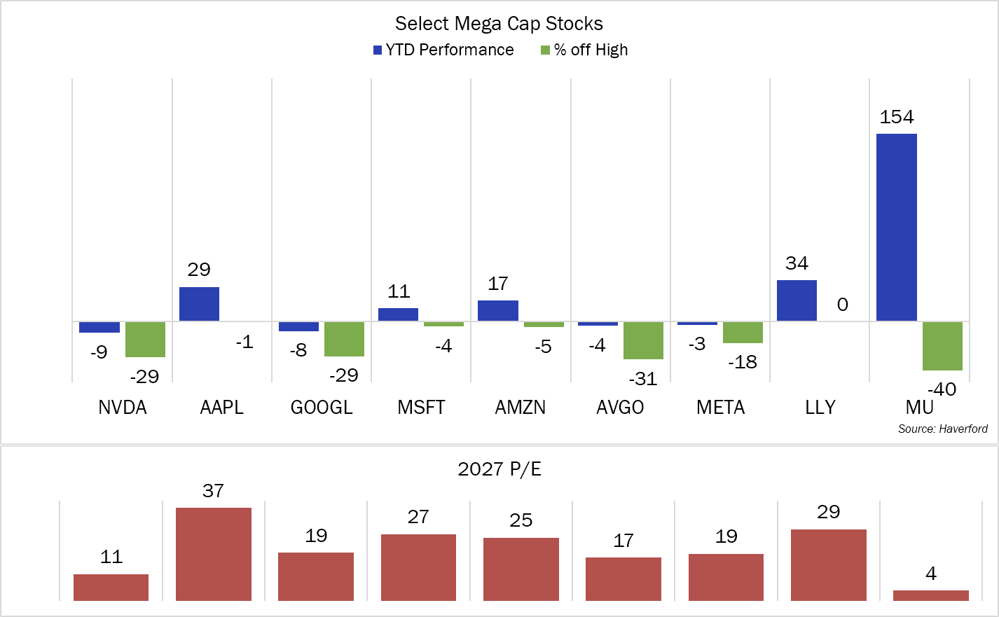
Mega Cap Stocks Perf vs PE
Sources: FactSet, Haverford. The 2027 price-to-earnings (P/E) ratios are a forecast.
About $300 billion of new equity has come to market in 2026, and more is expected, including the upcoming Anthropic offering. While the supply of new stock could be a near-term headwind to markets, there is also a strong probability that a successful Anthropic IPO renews enthusiasm for the AI trade and provides the company with the cash needed to help meet its data center obligations.
Broader strength beneath the surface is a positive
While AI leaders have pulled back, the market’s underlying strength has been encouraging. Rotations into other sectors have supported diversification beyond big tech, and the market is no longer relying on a handful of names to carry returns. As of November 6, 2026, the total market was trading at around 18x forward earnings, lower than at Liberation Day on April 2, 2025. That has occurred even as next-year earnings estimates have risen to a level that FactSet consensus estimates at roughly 16% growth. With healthy participation from other areas of the market and reasonable valuations, we generally see the current environment as a decent entry point.
Investment implications
The market is demanding more evidence that the enormous amount of AI infrastructure spending will generate durable cash flow. As the cycle progresses, these types of market pullbacks are expected. However, we continue to think that AI remains a compelling opportunity, and we believe many of these companies can continue to deliver returns. As long as the overall thesis remains intact, we will remain patient and disciplined. These market corrections can provide an opportunity to add high-conviction AI exposure incrementally at attractive valuations. We believe our focus on quality, long-term growth, balance sheet strength, diversification, and dividends is well suited for volatile markets.
Media Inquiries
Veronica McKee, CMP, CMM
Direct Phone: 610.995.8758
Email: vmckee@haverfordquality.com
Katie Karsh
Direct Phone: 610.755.8682
Email: katie@gobraithwaite.com
Disclosure
These comments are provided as a general market overview and should not be relied upon as a forecast, research or investment advice, and is not a recommendation, offer, or solicitation to buy or sell any securities or to adopt any investment strategy. Opinions expressed are as of the date noted and may change at any time. The information and opinions are derived from proprietary and non-proprietary sources deemed by Haverford to be reliable, but are not necessarily all-inclusive and are not guaranteed as to accuracy. Index returns are presented for informational purposes only. Indices are unmanaged, do not incur fees or expenses, and cannot be invested in directly.
Investments in Securities are Not FDIC Insured · Not Bank Guaranteed · May Lose Value
Related News & Insights
AI-related stocks have been volatile both before and after the U.S. election. Even before voters went to the polls, investors were questioning the return on investment from massive capital spending and the growing debt obligations tied to data center buildouts. However, we expect strong demand for compute to continue as enterprises increasingly recognize the outsized potential that AI can provide.
AI's dominance has resulted in an extremely narrow equity market driven by a handful of mega-cap tech names, creating concern that corrections in these stocks will drag down the broader market. However, October proved different. Although the AI trade weakened, the rest of the market finally began to carry more of the load.
With just days until the U.S. midterm elections, it is nearly impossible to escape the political news cycle. However, election results historically have had less impact on market performance than political candidates would have one believe.
